


We Connect Asia

SOUTHEAST ASIA

Malaysia's Biogas Feed-in Tariff:
The Real Trade-Off Between Local Use, PPA, and Grid Injection

7 min read  ·  Nov 26, 2025  ·  By Alex

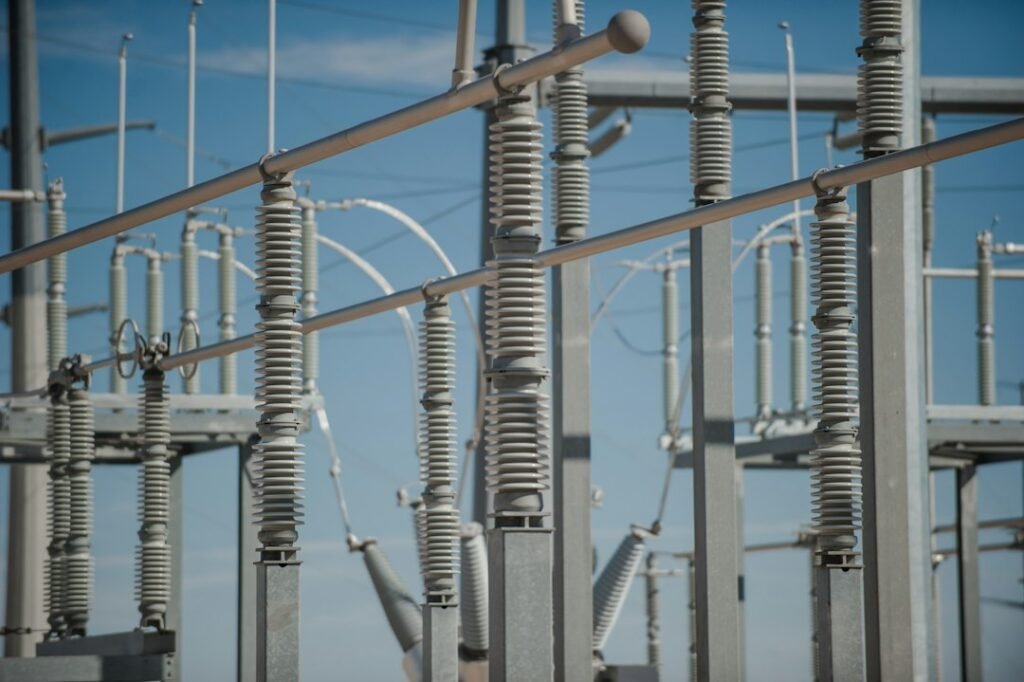
Electrical power transmission infrastructure

Every palm oil mill owner I talk to who’s sitting on untapped biogas eventually asks the same practical question. Should I run a gas engine and use the power myself? Or should I sell the power under a bilateral PPA, or take the Feed-in Tariff route to the grid? Malaysia’s FIT mechanism makes the grid route look attractive on paper. In fact, the choice comes down to one thing most developers underweight at the feasibility stage. How far are you from a point the grid can take your power?

In short: Malaysia’s Feed-in Tariff requires Distribution Licensees like TNB to buy renewable electricity from Feed-in Approval Holders. The guaranteed rate lasts 16 years for biogas. That’s a real, long-tenor revenue guarantee. But it only pays off once you’ve built and financed the interconnection facilities to reach the grid. That is where distance, cost, and approval timelines start eating into the FIT’s advantage. You can instead run a Jenbacher engine for your own consumption, or sign a direct PPA.

Facebook
Twitter
LinkedIn

In this article

How the FIT mechanism actually works

Under the FIT framework, Distribution Licensees such as TNB, SESB, and NUR must buy power from Feed-in Approval Holders. Those holders carry a feed-in approval certificate from SEDA Malaysia. For biogas and biomass, that purchase obligation runs for 16 years at a fixed premium rate. It’s a genuinely long revenue horizon that most bilateral PPAs never match.

Getting there requires working through a defined sequence. Firstly, secure site rights and financing. Then complete a Power Systems Study (for installations above 180 kW) or a Connection Confirmation Check (for 72-180 kW). Secondly, sign a Renewable Energy Power Purchase Agreement (REPPA) with the DL and register it with SEDA. Thirdly, obtain a provisional and then permanent generation licence from the Energy Commission. Finally, build the generating plant and interconnection facilities, and install the FIT meter. Acceptance testing comes last and must finish before the FIT Commencement Date. The Power Systems Study alone carries a published fee schedule. Fees run RM20,000 for up to 1 MW and RM40,000 for 1-10 MW, with a 30-day review period. That’s before any construction begins.

The dilemma: local consumption, PPA, or grid injection

Route Main advantage Main constraint
Local/on-site consumption No interconnection build-out needed; displaces your own retail power cost immediately Capped by your own site’s demand; surplus gas has nowhere to go
Bilateral PPA to a nearby buyer Can be negotiated faster than the FIT process; flexible terms No guaranteed long tenor; still typically needs some grid-adjacent interconnection unless the buyer is directly wired to you
FIT grid injection 16-year guaranteed purchase obligation at a fixed rate Full interconnection build cost and multi-step regulatory process; economics depend heavily on distance to the point of connection

For a palm oil mill or agricultural operation generating biogas via a Jenbacher-style gas engine, one question matters. The honest comparison isn’t “which pays the highest tariff,” it’s “which option actually clears my site’s specific interconnection reality.” A mill 500 meters from an existing medium-voltage line faces a completely different capex picture. Compare it with a site 8 kilometers from the nearest point the grid can accept new generation.

Where this breaks in practice

  • Underestimating the cost of distance to the point of interconnection. Building the generating plant and interconnection facilities, cabling, substation work, and protection equipment, is explicitly the developer’s responsibility. That rule is part of the FIT process. A site far from existing grid infrastructure can see interconnection capex match or exceed the generation equipment cost.
  • Treating the Power Systems Study timeline as the whole approval clock. The 30-42 day PSS review is only one step. The full sequence, site rights, REPPA signing and SEDA registration, provisional and then permanent Energy Commission licensing, interconnection construction, FIT meter installation, and acceptance testing, routinely runs well beyond that single study window.
  • Assuming on-site consumption or a PPA avoids regulatory complexity entirely. Even a direct PPA to a nearby industrial buyer, or substantial on-site generation, can trigger its own technical and safety approval requirements if it interacts with grid-connected infrastructure at all, so “simpler” doesn’t always mean “approval-free.”
  • Locking into a 16-year FIT obligation before confirming the interconnection economics work. The FIT’s long tenor is attractive, but it’s only valuable if the interconnection capex and timeline don’t erode the project’s returns before revenue even starts flowing.

A practical method for choosing your route

  1. Map your actual distance to the nearest viable point of interconnection before comparing tariff rates. Since this single factor often decides the outcome, it matters more than the FIT rate itself.
  2. Size your on-site consumption potential first, since any gas you can use directly avoids interconnection costs entirely. It provides immediate, delay-free value.
  3. Get a real interconnection cost estimate, not a rule of thumb, before committing to the FIT route. The Power Systems Study fee and timeline are only the starting point of the real cost.
  4. Compare the FIT’s 16-year guaranteed tenor against a realistic bilateral PPA term for your specific buyer relationship. Don’t assume the FIT is automatically superior because it’s longer.
  5. Sequence your licensing and construction activities in parallel wherever regulations allow. Otherwise, the full approval chain runs serially and extends your time to revenue.

Common mistakes I see developers and mill owners make

  • Comparing FIT, PPA, and on-site consumption purely on headline tariff or price without modeling the site’s actual interconnection distance and cost.
  • Treating the Power Systems Study’s 30-42 day timeline as the full approval and construction schedule.
  • Committing to a 16-year FIT obligation before confirming interconnection capex won’t erode the economics.
  • Assuming a bilateral PPA sidesteps all regulatory and technical approval requirements.

A quick checklist before you take this to lenders

  • A mapped distance and real cost estimate to your nearest viable point of interconnection
  • An on-site consumption sizing exercise completed before evaluating external sale routes
  • A Power Systems Study or Connection Confirmation Check already scoped, with its fee and timeline built into your project schedule
  • A REPPA and SEDA registration pathway clearly sequenced against your Energy Commission licensing steps
  • A side-by-side economic comparison of FIT, PPA, and on-site consumption using your site’s actual numbers, not generic benchmarks

Sources

FAQ

Building the generating plant and the interconnection facilities is the developer’s responsibility as part of the FIT application process. Those costs include cabling, substation work, and protection equipment to reach the Distribution Licensee’s network. The project itself has to carry them, and they scale significantly with distance from existing grid infrastructure.

The FIT purchase obligation for biogas and biomass runs for 16 years at a fixed premium rate. That’s a long enough tenor to be genuinely useful for long-term financing. It works, provided the interconnection economics and approval timeline don’t erode the project’s returns before that revenue starts.

It avoids interconnection build-out entirely, which is a real advantage. But your own site can only use so much power. Any surplus gas beyond that cap has no outlet unless you also pursue a PPA or FIT route. So most developers end up evaluating a combination rather than a single option exclusively.

If you’re weighing local consumption, a PPA, or the FIT grid route, that’s a site-specific question. It’s exactly the kind of question I help developers and mill owners think through. Get in touch and we can look at your numbers together.

I’m part of the WeConnect Asia team, working with developers and investors on low-carbon infrastructure projects across Southeast Asia.

This article is for general informational purposes and does not constitute financial, legal, or engineering advice. Figures cited come from publicly available SEDA Malaysia materials. Independently verify them against current rates and regulations before use in any financial model.

Not sure your project would survive a credit conversation?

A short call is usually enough to see where your project stands against what a lender or an equity investor will ask for. Tell me where your project is today, and I will tell you what the next conversation needs to look like.

Alex, Founder of WeConnect Asia

Alex, Founder of WeConnect Asia

I help low-carbon fuel and carbon removal project developers in Southeast Asia secure the commercial and financial partners needed to reach FID.

More about me·Get in touch

Facebook
Twitter
LinkedIn

Related articles




