
Home » Why Most Biochar Projects Aren’t Bankable, and What Changes the Math
Why Most Biochar Projects Aren't Bankable, and What Changes the Math
15 min read · Aug 3, 2026 · By Alex
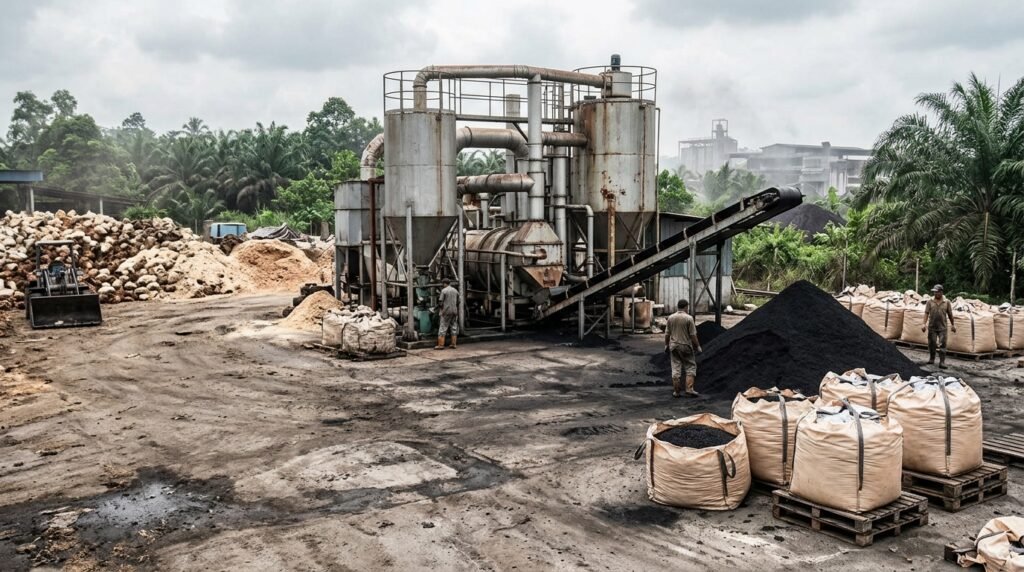
Most of the biochar projects I have looked at across Malaysia, Indonesia and India never make it past the first serious credit conversation. The reason is almost never the pyrolysis technology. Biochar project bankability usually fails further down the line, in the financing story rather than in the plant. The agricultural case is usually solid: real feedstock, real soil benefits, a willing community of farmers. What falls apart is that financing story.
Most of the developers who come to me already have a solid project on paper. The agricultural case works. What they usually bring with them is a string of refusals. Here is the scene that plays out before they call me. A developer walks into a room with a strong case for biochar as a soil amendment, improved yields, water retention, reduced crop burning. A lender or an investor listens politely, then asks the question that ends most of these meetings: what exactly am I buying, and which cash flow repays me? When the answer is “biochar sales to local farmers,” nobody finances it, whatever the farming side looks like on paper.
A biochar project becomes hard to finance the moment the market treats it as a soil amendment business. It becomes bankable the moment its sponsor structures it as a carbon removal business, with feedstock secured under contract and carbon credits sold under contract, and ideally with revenue coming from more than just the char itself. That shift, from agricultural product to carbon removal infrastructure, is the single biggest driver of biochar project bankability I have seen across the projects I have worked on in the region.
What this article covers
This article sets out what separates a low-bankability biochar project from one that gets through a credit committee. A companion piece, How Carbon Removal Makes a Biochar Project Bankable, goes deeper into the mechanics of the carbon removal side specifically: methodology choice, MRV, and how a sponsor structures a forward credit sale. Read this one first if you are still deciding whether your project is investable at all.
In short
- Investors and lenders routinely pass over biochar projects sold as a soil amendment business with a single uncontracted revenue stream, regardless of the technology.
- Scale matters more than most developers expect. Aggregating agricultural residue below roughly 50,000 tonnes a year puts a project below the size that institutional investors and specialised funds will typically look at.
- A chosen carbon removal methodology (Puro.earth, Verra, Isometric or equivalent) and a credit offtake agreement turn a single, fragile revenue line into something closer to a contracted cash flow.
- Long-term feedstock contracts are what convert “there is biomass nearby” into something a bank can underwrite.
- The most bankable projects add revenue from the 60 to 70 percent of carbon that does not end up in the char, through heat, power, or liquid and gas products.
In this article
What a low-bankability biochar project looks like
Across the projects I have reviewed in Malaysia, Indonesia and India, the ones that struggle to raise money share a recognisable profile. Low biochar project bankability looks the same almost everywhere. None of this is about any one project. It is the pattern.
Standalone, farmer-facing, with no pipeline. Small units producing biochar for local farmers, usually built and run by a small operator or an NGO rather than a structured platform. There is nothing wrong with the mission. There is also nothing here that an investor can scale into a portfolio.
No carbon strategy at all. No one has selected a carbon removal methodology, and no measurement, reporting and verification (MRV) process exists. There is no plan to generate or sell carbon credits. From a financier’s point of view, that is a single, thin revenue stream: biochar sold as a soil input. The market is not particularly solvent, and prices are low and volumes uncertain.
No long-term feedstock contracts. Operators buy biomass as it becomes available, with no written agreements on volume, price or quality. To a lender, this reads as a direct risk of plant downtime or margin erosion. It is one of the fastest ways to lose a financing conversation.
Scale and technology risk
Sub-scale production. Most of these projects process well under 50,000 tonnes of biomass a year. That is simply too small to interest institutional investors or the funds that specialise in carbon removal or climate infrastructure, whose minimum ticket sizes do not justify the diligence cost on a small deal.
Technology without a track record at the intended scale. Either the team has not demonstrated the pyrolysis unit at the volumes the project is planning, or the equipment supplier does not have a credible history. For an investor, that becomes a technology risk layered on top of everything else.
Put together, a project with low volume, no track record, unvalidated technology at scale, no structured carbon strategy, and no feedstock contracts looks, to a credit committee, too small, too risky, and insufficiently secured to justify a meaningful ticket. It reads as a pilot, not as an asset.
What a bankable biochar project looks like
The projects that investors finance look structurally different, not just better run.
Large-scale residue aggregation. Biomass aggregated across a wide agricultural area, typically at 50,000 tonnes a year or more. That threshold signals an industrial project rather than a micro-site, and it is roughly the scale where specialised investors start paying attention.
A recognised carbon removal methodology. The project uses an established standard, Puro.earth, Verra with the Isometric or equivalent registries, rather than an informal carbon claim. Isometric has gone further still, certifying a methodology for biochar stored in underground mines with durability claims running to a thousand years (Carbon Pulse). The specific methodology matters less than the fact that the team chose one early and keeps following it, because that is what makes the resulting credits sellable on premium markets and acceptable to auditors.
A structured carbon credit offtake. Forward purchase agreements with identified buyers give visibility on volume, price and duration. Platts has reported offtake price indications of roughly $80 to $120 per tonne of CO2e for industrial biochar credits certified by Puro Earth or Isometric, against spot prices closer to $140 to $150 per tonne (S&P Global). One Bengaluru-based market participant summed up what I hear from investors directly: the first question is always whether sponsors will sign an offtake, and investors frequently pass over projects without one regardless of quality.
Proven technology, and revenue beyond biochar
Industrial-scale pyrolysis with a track record. Suppliers have already proven the technology elsewhere at comparable volumes, which removes a layer of technology risk for the financier.
Revenue from the fraction that is not char. Biochar typically represents only 30 to 40 percent of the carbon in the original feedstock. The remaining 60 to 70 percent leaves the reactor as a liquid or gas fraction. The most bankable projects either monetise this directly, through heat and power generation, or build a credible pathway toward bio-oil, biomethanol, sustainable aviation fuel or other bioproducts. Citi’s recent $72 million carbon removal-linked note for Applied Carbon’s biochar project in Texas is a useful marker here: the structure pays investors from the issuance and delivery of carbon credits rather than a fixed coupon, and Applied Carbon’s own framing was that biochar projects can be “structured and financed like any other asset” once the credit and offtake mechanics are in place (Citigroup).
The shift, in plain terms: a project moves from “selling an agricultural product” to “operating carbon removal infrastructure” when it has several revenue lines (credits, biochar, by-products or energy), each backed by a contract (feedstock supply, credit offtake, product offtake), supported by mature technology, at a scale that clears the threshold institutional capital actually looks at.
The feedstock base is already there in Southeast Asia
Developers often treat scale as the hardest constraint to solve. In this region it is usually a structuring problem rather than a feedstock problem. Palm oil plantations in Indonesia and Malaysia alone generate an estimated 140 million tonnes of unused biomass a year. Most of it is empty fruit bunches and oil palm trunks. Those residues are fibrous and high in moisture, and standard reactors have historically struggled to process them. One industry estimate puts the theoretical ceiling on durable carbon removal from this residue stream at around 32 million tonnes of CO2 a year. It is a potential figure rather than a demonstrated one. It shows how far current project scales are from the regional ceiling (BiocharToday).
The region also already has a working proof point on the carbon revenue side, even at small scale. In the Philippines, the provincial government of Nueva Ecija built a rice husk biochar plant that Puro.earth independently audited and certified for carbon removal in 2023, and it received its first carbon revenue remittance in 2025, reportedly the first biochar project in Southeast Asia to monetise credits this way (BiocharToday). The volumes involved were modest, a few hundred tonnes of biochar across roughly 180 hectares, but the structure, third-party verification followed by an actual revenue payment, is exactly the pattern that scales.
What this tells a developer in the region: the biomass is there, and the market has already shown that verification plus offtake produces real cash flow. The gap between most biochar projects and bankability is rarely the resource. It is almost always feedstock contracting, methodology choice, and scale of aggregation.
What a lender checks versus what an equity investor checks
| Lender | Equity investor | |
|---|---|---|
| First question | Is there a signed, priced offtake for the credits? | What is the exit, and who else is in the deal? |
| Feedstock | Written, multi-year contracts with volume, price and quality clauses | Security of supply at the scale needed to grow, not just to operate |
| Technology | Proven at comparable scale, with an operating track record | Enough technology risk to justify equity returns, but not more than the team can manage |
| Revenue | Contracted and diversified, able to service debt in a downside case | Multiple upside levers: by-products, pipeline expansion, carbon price appreciation |
| Scale | Large enough that fixed costs are covered even in a weak quarter | Large enough to be worth the diligence and board time |
Where biochar project bankability breaks in practice
A few patterns show up again and again, across markets and across technologies.
The carbon strategy arrives too late. Developers often build the plant first and start thinking about methodology and MRV once production has started. By then, the registration process, the monitoring plan and the early credit vintages have already lost value, and investors notice the gap.
Feedstock agreements exist in principle, not in writing. A developer will describe strong relationships with suppliers, cooperatives or aggregators, but when asked for the signed contract, there is a verbal understanding instead. For a bank, an unwritten agreement is not an agreement.
Volumes stay just under the threshold that matters. Many developers design projects around what they can source locally rather than what the project needs to be investable. The gap between, say, 20,000 and 50,000 tonnes a year is often the gap between “interesting” and “financeable.”
Nobody has analysed the non-char fraction. Even projects with a reasonable carbon story frequently have no data on the liquid or gas fraction coming off the reactor, which closes off a revenue line that more mature projects are already using.
Four moves that change biochar project bankability
1. Decide on day one that this is a carbon removal business, not a soil amendment business. Everything downstream, methodology, contracts, data room, follows from this choice, and it is far cheaper to make early than to retrofit later. 2. Lock feedstock before you lock anything else. Multi-year, written contracts with volume, price and quality terms, ideally with more than one supplier. 3. Choose a methodology and start selling credits forward. This is the part that changes the finance math the most, and it deserves its own deep dive, which is what the companion article on CDR covers in detail. 4. Map the non-char fraction honestly. Even a modest, credible plan for heat or power beats no plan at all, and a signed letter of intent from an industrial buyer for bio-oil or biomethanol is worth more than a slide describing the potential.
Common mistakes that cost biochar project bankability
- Treating the carbon credit as a bonus on top of the “real” biochar business, rather than as the core product.
- Negotiating feedstock supply informally because the relationships are genuinely good, then discovering a lender will not count a handshake as security of supply.
- Picking a scale based on available land or available biomass locally, rather than the scale institutional capital actually finances.
- Delaying MRV and methodology work until construction ends.
- Presenting biochar quality data without any parallel data on the carbon removal performance or the non-char fraction.
A short biochar project bankability checklist
- Volume: is feedstock aggregation realistically above roughly 50,000 tonnes a year, now or on a credible near-term path?
- Methodology: did the team choose a recognised carbon removal standard, and is MRV running from day one?
- Feedstock: are supply contracts written, multi-year, and do they cover volume, price and quality?
- Carbon revenue: is there a forward offtake, or at minimum active conversations with identified credit buyers?
- Technology: can you point to comparable operating history at the scale you are planning?
- By-products: do you have real data, even preliminary, on the non-char fraction and a plan for it?
Next step
If you are developing a biochar project and are not sure whether it would survive a real credit conversation, the questions worth asking first are simple: what is your scale, do you have a chosen methodology, and do you have anything in writing with your feedstock suppliers. A short call is usually enough to see where the project stands. You can book one directly here, or read the Roadmap to Bankability for the broader picture beyond biochar specifically.
For the mechanics of turning the carbon removal side of a biochar project into something a lender can model, the companion article, How Carbon Removal Makes a Biochar Project Bankable, goes into the methodology, MRV and offtake structuring in detail.
Sources
- S&P Global / Platts: Biochar developers diversify beyond carbon credits as market evolves (Oct. 2025)
- S&P Global / Platts: Strong appetite for biochar carbon projects in India, offtakes essential (Oct. 2025)
- Citigroup: Citi closes $72 million carbon removal-linked note to support Applied Carbon biochar project (Oct. 2026)
- S&P Global: Indonesia may emerge as next major biochar credits producer in SE Asia after India (Aug. 2026)
- Carbon Pulse: Isometric certifies carbon removal methodology for storing biochar in underground mines
- BiocharToday: TSE Group collaborates to establish scalable palm biomass biochar systems in Southeast Asia (June 2026)
- BiocharToday: Nueva Ecija and Alcom Carbon Markets achieve Southeast Asia’s first biochar carbon credit revenue
FAQ
Why do investors reject biochar projects that are technically sound?
Because technical soundness is not the same as bankability. A lender or investor needs predictable, contracted cash flow. A project that sells biochar as a soil amendment, with no carbon credit strategy and no feedstock contracts, has neither, no matter how well the pyrolysis unit performs.
What is the minimum scale for a biochar project to attract institutional capital?
There is no universal number, but across the projects I see, roughly 50,000 tonnes of biomass a year is the point where specialised investors and funds start to engage seriously. Below that, the deal size often does not justify the diligence required.
Does a biochar project need a signed carbon credit offtake before raising capital?
It helps enormously. Market participants report that investors often make this their first question and pass on projects without one, even when the underlying project is sound. At minimum, you need active, documented conversations with identified buyers.
How much of a biochar project's revenue should come from carbon credits versus biochar sales?
It depends on the project, but the most resilient structures I have seen rely on at least two or three distinct revenue lines, typically carbon credits, physical biochar or by-product sales, and sometimes energy generation, rather than a single stream.
What happens to the part of the biomass that doesn't become biochar?
Biochar usually accounts for only 30 to 40 percent of the carbon in the feedstock. The rest leaves the process as a liquid or gas fraction, which plants can use for heat and power, or upgrade into higher-value products such as bio-oil, biomethanol or sustainable aviation fuel. Projects that ignore this fraction are leaving a revenue line, and a bankability argument, on the table.
Is Southeast Asia a credible region for bankable biochar projects?
Yes, and increasingly so. India has moved fastest on biochar carbon credit volumes, and Indonesia is now seen by market participants as the next major producer in the region, partly because of its large potential feedstock base (S&P Global). Malaysia, Thailand, the Philippines and Cambodia are also developing projects, though participants are still watching whether they can match that pace collectively.
Not sure your project would survive a credit conversation?
A short call is usually enough to see where your project stands against what a lender or an equity investor will ask for. Tell me where your project is today, and I will tell you what the next conversation needs to look like.

I am Alex, founder of WeConnect Asia, based in Kuala Lumpur. My work supports low-carbon fuel and carbon removal project developers across Southeast Asia, from first contact to FID. The commercial and financial partners they need span capital raising, project finance, offtake agreements, feedstock supply and strategic partnerships. I do not provide investment advice or arrange investments. I act as a strategic advisor and facilitator.
Related articles

Biomethane: What It Is, How It Is Made and Who Buys It
Biomethane is biogas cleaned to pipeline quality. I explain how it is made, how it differs from biogas and who buys it in Southeast Asia.

Southeast Asia SAF: Policies, Demand and Project Status
Southeast Asia SAF policy is moving country by country. Here is where demand is forming, who the buyers are and what a developer can rely on today.

e-SAF Project Finance: Why the Sub-Mandate Is Not Enough
The synthetic fuel sub-mandate creates demand for e-SAF, but not a bankable project. Here is what e-SAF project finance still needs in Southeast Asia.

SAF Mandates by Country: A Developer’s Comparison
SAF mandates differ by country in scope, target and penalty. Here is a side-by-side comparison and what each one means for project revenue.

Sustainable Aviation Fuel: Pathways, Mandates and What Gets Financed
Sustainable aviation fuel has several pathways and sells into mandates. I explain the routes, the demand and what gets financed in Asia.

ReFuelEU Offtake: Who Actually Buys Your SAF?
The ReFuelEU mandate sits on fuel suppliers, not airlines. Here is what that means for ReFuelEU offtake contracts and what lenders expect to see.